Britain's borrowing costs hit a 27-year high
Fiscal rule headroom erodes with yields
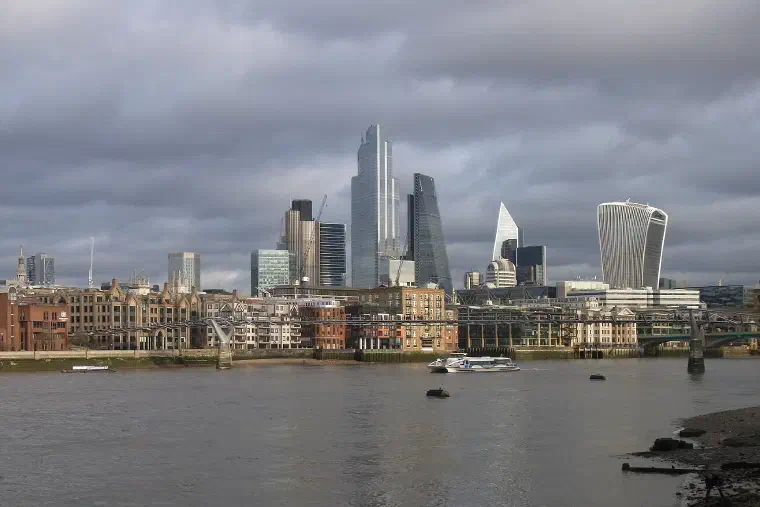
The yield on British 30-year government bonds has breached 5.47 per cent, touching levels not seen in twenty-seven years and sending severe warning signals through HM Treasury. The sell-off reflects an unforgiving sovereign risk premium demanded by international investors confronting persistent UK inflation, rising borrowing requirements, and wafer-thin fiscal headroom under statutory budget rules.

Headroom Erosion Arithmetic
The transmission mechanism from gilt yields to government fiscal plans is direct and unforgiving. Under the government's fiscal framework, debt must be projected to fall as a share of GDP within five years. However, every 50-basis-point upward shift in the gilt curve wipes out roughly £5 billion in projected fiscal headroom due to surging debt-servicing costs. With 30-year yields anchored above five per cent, Chancellor Rachel Reeves's planned capital investments are being crowded out by the compounding cost of servicing outstanding obligations.

Institutional Collateral Strain
Unlike the LDI liquidity crisis of 2022, this repricing represents a slow, grinding loss of investor confidence rather than a sudden leverage squeeze. High-yielding sterling paper fails to attract sustained foreign bids when the structural current account deficit remains unhedged. The UK sovereign bond market has decisively re-established its fiscal boundary: debt-funded public investment cannot outrun the unforgiving arithmetic of a five-and-a-half per cent benchmark borrowing rate.